Would you like to change the market?
Select area of operation
You will be redirected to another page for the selected market
FAQ
Would you like to change the market?
Select area of operation
You will be redirected to another page for the selected market

    Blog

    Check our blog

    Learn more about the latest industry trends, changes in regulations and development opportunities for your company.
    30 October, 2024

    VAT in real estate transactions

    Understanding the rules that apply to the taxation of real estate transactions is essential for anyone operating in the market, whether investors,...

    28 February, 2025

    Omnibus package – incoming changes in ESG reporting

    The European Commission’s proposals to simplify ESG regulations as part of the so-called Omnibus Package published on February 26th 2025 have sparked...

    Latest

    • PPWR 2026: What requirements will e-commerce businesses need to meet from 12 August?

      The Packaging and Packaging Waste Regulation (PPWR) – Regulation (EU) 2024/1781 – will apply from 12 August 2026. Replacing Directive 94/62/EC, which has governed packaging and packaging waste since 1994, the new regulation introduces significant changes across several areas.

      For many e-commerce businesses, the PPWR is primarily associated with extended producer responsibility (EPR), which requires companies to register with national authorities and pay fees for packaging placed on the market. This is understandable, as EPR is one of the most widely discussed aspects of the regulation. However, the PPWR goes considerably further, introducing specific requirements for packaging design, recyclability, recycled content and labelling. It also places greater emphasis on reusable packaging, an issue of particular importance to online retailers.

      The obligations that apply to a business also depend on its role in the supply chain. Manufacturers, importers, distributors, retailers operating their own online stores and marketplace sellers are all subject to different requirements. A single business may fulfil several of these roles simultaneously.

      In this article, we examine the key PPWR requirements affecting e-commerce businesses, including the relevant deadlines and the obligations associated with each role.

      What is the PPWR and how does it differ from existing legislation?

      PPWR stands for Packaging and Packaging Waste Regulation, the EU regulation governing packaging and packaging waste.

      Unlike the previous legislation, the PPWR extends beyond packaging waste management to cover the entire packaging lifecycle, from design and recyclability to labelling and information requirements. Extended producer responsibility (EPR) is just one element of this broader regulatory framework.

      Another significant change for e-commerce is that the PPWR explicitly addresses distance selling and online marketplaces. The previous directive was introduced before the rapid growth of e-commerce and did not contain specific provisions for online sales.

      What is your role under the PPWR, and how does it affect your obligations?

      The PPWR defines several roles within the packaging supply chain. The requirements that apply to your business depend on which role, or combination of roles, it fulfils.

      Producer

      Under Article 3(1)(11) of Regulation (EU) 2024/1781, a producer includes an entity that:

      • Manufactures or packages products under its own brand and places them on the domestic market.
      • Resells products supplied by other businesses under its own brand.
      • Places products originating from another EU Member State or a non-EU country on the domestic market.
      • Sells products online directly to consumers in another EU Member State, even if the business is established in Poland.

      The final point is particularly relevant to Polish e-commerce businesses engaged in cross-border sales. A company selling directly to German consumers through its own online store is considered a producer in Germany for PPWR purposes and must therefore fulfil the corresponding obligations in that market.

      Importer

      An importer is an entity established in the EU that places packaging or packaged products manufactured outside the EU on the market. If a manufacturer based outside the EU (e.g. China, South Korea or Turkey), has not appointed an authorised representative in the EU, the importer assumes responsibility for meeting the relevant PPWR requirements. In practice, this means ensuring that the packaging complies with applicable design, labelling and EPR requirements, as though the importer had manufactured it.

      Distributor

      A distributor is an entity that makes packaging or packaged products available on the market without being their manufacturer or importer. Although distributors are not directly responsible for meeting packaging design requirements, they must verify that their suppliers, whether manufacturers or importers, fulfil their obligations. A distributor may also incur secondary liability if it places products on the market despite knowing, or having reasonable grounds to believe, that the supplier has failed to comply with the PPWR.

      E-commerce retailer using shipping packaging

      Any e-commerce business that dispatches products to customers uses transport or shipping packaging. The PPWR introduces packaging minimisation requirements, including the maximum 40% empty space rule, alongside targets for reusable packaging. These requirements apply regardless of whether the business is classified as a producer, importer or distributor.

      Marketplace seller

      Businesses selling through platforms such as Amazon, Zalando, Allegro or eBay must meet the same PPWR requirements as retailers operating their own online stores. The main difference is that, from 12 August 2026, marketplace operators will be required to collect EPR registration numbers and packaging declarations of conformity from sellers, and restrict access for businesses that do not hold the required registrations.

      Overview of roles and responsibilities


      RoleE-commerce examplePackaging minimisationEPRLabellingReusable packaging
      ProducerOwn-brand retailer, cross-border sellerYesYesYesYes
      ImporterBusiness importing products from Asia or the UKYesYesYes, if not addressed by manufacturerYes
      DistributorWholesaler or reseller of third-party brandsYes, for its own transport packagingSupplier verificationSupplier verificationYes, for its own packaging
      E-commerce retailer shipping productsAny online business dispatching ordersYesDepends on roleDepends on roleYes
      Marketplace sellerSeller on Amazon, Allegro or ZalandoYesYes, as required by the platformYesYes

      Not sure which PPWR requirements apply to your business?

      We’ll help you identify your role, understand the requirements across different markets, and prepare your business for PPWR compliance.

      Check your PPWR obligations

      Obligation 1 – EPR: How does the PPWR change existing requirements?

      Many e-commerce businesses are already registered under EPR schemes in selected countries, such as LUCID in Germany, UIN in France and CONAI in Italy. So what changes does the PPWR introduce to extended producer responsibility?

      A harmonised definition of producer

      Until now, each Member State has applied its own definition of a producer for EPR purposes. This has led to gaps and inconsistencies: businesses required to register in one country have sometimes been exempt in another because of differences in national interpretations.

      From 12 August 2026, the harmonised definition of producer under Article 3 of the PPWR applies across all EU Member States. Selling products online to consumers in a particular EU country therefore triggers an EPR registration obligation in that market, without the exemptions previously available under certain national rules.

      Expanded reporting requirements

      The PPWR broadens the range of packaging covered by registration and reporting obligations. Businesses will need to report on additional types of packaging, including e-commerce shipping packaging and grouped packaging. Reporting will also require more detailed breakdowns by packaging material and category.

      Higher recycling targets

      The PPWR increases the minimum national packaging waste recycling targets that producer responsibility organisations (PROs) must achieve. These higher targets may, in turn, lead to increased EPR fees for producers.

      Comparison: Existing EPR requirements and the 2026 PPWR

      AreaExisting requirementsFrom 12 August 2026
      Definition of producerVaries between countries, creating inconsistenciesHarmonised definition covering cross-border e-commerce
      Registration requirementsCountry-specific obligations requiring individual assessmentRegistration required when selling into an EU market
      Reporting requirementsLimited scope, varying by countryExpanded reporting covering additional packaging categories and materials
      Packaging minimisationNo EU-wide requirementMaximum 40% empty space and restrictions on unnecessary double walls
      RecyclabilityPrimarily voluntary declarationsMandatory assessment from 2026; grades A or B required from 2030
      Recycled contentNo mandatory minimumMinimum recycled content requirements for plastic packaging from 2030
      LabellingNational, non-harmonised requirementsHarmonised material codes and QR codes from 2028
      Reusable packagingNo specific e-commerce target10% by 2030 and 50% by 2040
      Online marketplacesNo general verification obligationRequirement to collect EPR information and restrict non-compliant sellers

      Obligation 2 – Packaging minimisation and design

      The maximum 40% empty space rule

      One of the most specific and operationally significant PPWR requirements concerns the amount of empty space permitted in transport and shipping packaging. Under this rule, empty space must not account for more than 40% of the total volume of a shipping package.

      Empty space refers to the space between the product, or its primary packaging, and the outer walls of the shipping package. It also includes void-fill materials such as bubble wrap, paper filling, polystyrene and air cushions ­­­– provided that the space they occupy is not necessary to protect the product.

      Example calculation: A cardboard box measuring 30 × 20 × 15 cm has a total volume of 9,000 cm³. The product and the protective materials needed to secure it occupy 5,000 cm³. This leaves 4,000 cm³ of empty space, equivalent to 44% of the package’s total volume. The package therefore does not meet the PPWR requirement. To achieve compliance, the box must be made smaller so that empty space accounts for no more than 40% of its total volume (≤ 3,333 cm³).

      This rule applies to shipping packaging selected by an e-commerce business when preparing an order for dispatch. It does not apply to a product’s original primary packaging as supplied by the manufacturer, unless the business is also responsible for manufacturing that packaging.

      Restrictions on unnecessary packaging features

      The PPWR prohibits packaging features such as double walls, false bottoms and other structural elements that make packaging appear larger without serving a protective or informational purpose. These restrictions are particularly relevant to presentation and gift packaging.

      Hazardous substances

      From 12 August 2026, packaging must not contain substances of very high concern (SVHCs) at concentrations exceeding the limits established under the REACH Regulation. This is particularly relevant to per- and polyfluoroalkyl substances (PFAS), which have traditionally been used in paper coatings for food packaging.

      For importers, this means checking the chemical composition of packaging supplied by manufacturers outside the EU and obtaining the necessary declarations of conformity before August 2026.

      Obligation 3 – Recyclability and recycled content

      Recyclability assessment (from 2026)

      From 12 August 2026, producers must assess the recyclability of their packaging in accordance with the methodology established by the European Commission through forthcoming delegated acts. The PPWR introduces a three-tier recyclability classification system:

      • Grade A: Packaging collected and recycled at scale, with more than 70% of the collected material stream undergoing effective recycling.
      • Grade B: Packaging that is technically recyclable but not yet recycled at scale because the necessary infrastructure is limited.
      • Grade C: Packaging that cannot be recycled using currently available methods.

      From 1 January 2030, packaging classified as Grade C may no longer be placed on the EU market. Producers and importers who fail to complete the necessary assessments by this deadline risk having their products blocked from sale.

      Minimum recycled content in plastic packaging (from 2030)

      The PPWR introduces mandatory minimum recycled content requirements for plastic packaging:

      • Plastic transport and shipping packaging, such as stretch film, packaging tape and plastic mailing bags: 35% recycled content from 1 January 2030.
      • Non-food plastic packaging other than bottles: 35% from 2030, increasing to 65% from 2040.
      • Non-food plastic bottles: 30% from 2030, increasing to 65% from 2040.

      Source: Regulation (EU) 2024/1781, Article 7 and Annex II, Part B.

      For e-commerce businesses using plastic packaging, such as mailing bags or stretch film for securing pallets, meeting these requirements may involve revising packaging procurement specifications or changing suppliers. Compliance will therefore require operational changes rather than a one-off administrative exercise.

      Obligation 4 – Reusable packaging in e-commerce

      Article 26(5) of the PPWR requires businesses using transport and shipping packaging to progressively increase the proportion of reusable packaging.

      “Reusable packaging”, as defined in the PPWR, is packaging designed and placed on the market for repeated use over multiple cycles. The minimum number of reuse cycles will be specified in delegated acts issued by the European Commission.

      Meeting the reusable packaging targets requires a structured approach. Simply labelling packaging as returnable will not be sufficient. Businesses aiming to meet the 10% target by 2030 should already be considering the following steps:

      • Exploring packaging pooling systems, where reusable packaging is shared between businesses, or deposit-return schemes.
      • Piloting reusable packaging with a selected group of customers.
      • Assessing the logistics involved in collecting and returning used packaging.

      Although the 2030 deadline leaves several years for implementation, experience with other EPR regulations suggests that businesses which delay preparations until the final year often struggle to meet their obligations on time.
      Obligation 5 – Packaging labelling

      The packaging labelling requirements set out in Article 12 of the PPWR take effect on 12 August 2028, two years after the regulation’s main application date.

      All packaging placed on the EU market will need to carry the following information:

      1. Material identification code: A harmonised code identifying the material from which the packaging is made, in accordance with Annex VI of the PPWR.
      2. Waste sorting instructions: A pictogram and accompanying information indicating the appropriate waste collection container.
      3. QR code or other data carrier: Providing additional information about the packaging material, composition, recyclability grade, producer and relevant EPR registration details.
      4. Reusable packaging label (where applicable): Information identifying the packaging as reusable, together with details of the return system and intended number of reuse cycles.
      5. Recycled content information (where applicable): Information indicating the proportion of recycled material used in the packaging.

      These requirements are particularly significant for importers: products imported from Asia or the United States typically do not carry labels that meet the new requirements. Importers who fail to ensure compliant labelling before August 2028 will have two options: relabel products after importation or revise their packaging specifications with overseas suppliers.

      The first option increases operating costs, while the second requires time for supplier negotiations and potential changes to manufacturing processes.

      Selling across the EU? Check your PPWR obligations

      We’ll help you understand your responsibilities across different EU markets and prepare for PPWR compliance.

      Check your requirements

      Online marketplaces – What changes for sellers and platform operators?

      For marketplace sellers

      Article 45 of the PPWR requires online marketplace operators to collect information from sellers confirming their EPR registration status and the conformity of their packaging with PPWR requirements. Platforms must verify that sellers hold valid EPR registrations in the countries where they sell their products while failure to hold the required registrations may result in account suspension.

      Amazon and Zalando already apply similar verification measures in selected markets, including Germany (LUCID) and France (UIN). Under the PPWR, these requirements will be extended to all EU markets served by the platforms and to all sellers.

      This means that, from 12 August 2026, sellers operating across Amazon’s German, French, Italian, Spanish, Dutch and Swedish marketplaces must hold valid EPR registrations in each of those countries, rather than only in Germany and France.

      For sellers established outside the EU

      A business established outside the EU, for example in China, the UK or the United States, that sells to EU consumers through Amazon EU is considered a producer under the PPWR, thus subject to the regulation’s requirements. The business may fulfil these obligations directly by registering in the relevant EU countries or through an appointed authorised representative.

      If a seller fails to comply, the marketplace operator, such as Amazon, may be held liable to the extent that it has failed to carry out the required checks, which in turn serves as a strong incentive to ensure that their sellers comply.

      For marketplace operators

      Marketplace operators must maintain up-to-date records of sellers’ EPR registration numbers, verify that registrations remain valid and restrict access for sellers that fail to meet the requirements. The extent of a platform’s liability depends on whether it knew, or reasonably should have known, that a seller was non-compliant.

      PPWR implementation timeline – Key dates and requirements

      DateRequirementBusinesses affected
      12/08/2026Packaging minimisation: maximum 40% empty space and restrictions on unnecessary double wallsAll businesses using shipping packaging
      12/08/2026Restrictions on hazardous substances (PFAS, SVHCs) in packagingProducers and importers
      12/08/2026Harmonised EPR requirements: registration and reporting under the PPWR definitionProducers and importers
      12/08/2026Marketplace obligations: collecting sellers’ EPR information and restricting non-compliant sellersMarketplace operators
      12/08/2026Packaging recyclability assessments and supporting documentationProducers and importers
      12/08/2026Packaging labelling: material codes, waste sorting instructions and QR codesProducers and importers
      01/01/20230Grade A or B recyclability required for all packagingProducers and importers
      01/01/20230Minimum recycled content requirements for plastic packagingProducers and importers
      01/01/2023010% reusable packaging target for e-commerce shipmentsE-commerce businesses shipping products
      01/01/204050% reusable packaging target for e-commerce shipmentsE-commerce businesses shipping products

      Where should you start? An action plan based on your role

      PPWR compliance involves more than completing a registration or submitting a declaration. It requires a series of decisions and operational changes, implemented in the right order. The following priorities can help you determine where to begin, depending on your business’s role.

      If you manufacture your own packaging

      Start by auditing your existing packaging to check whether it meets the maximum 40% empty space requirement and complies with the restrictions on substances of very high concern (SVHCs). These requirements apply from 12 August 2026, making them an immediate priority. Packaging changes take time, particularly when they involve redesign, testing and new procurement arrangements.

      At the same time, consider assessing the recyclability of your packaging, even before the European Commission finalises the methodology through delegated acts. Identifying packaging that requires material changes at an early stage can help you avoid costly last-minute modifications.

      If you import products from outside the EU

      Your priority should be to establish whether your overseas supplier or manufacturer has appointed an authorised representative in the EU and whether its packaging meets the PPWR requirements. If these conditions are not met, the importer assumes responsibilities equivalent to those of a producer, so consider including specific PPWR compliance clauses in new supplier contracts.

      You should also verify the chemical composition of the packaging, particularly its PFAS and SVHC content, and assess whether imported products will meet the labelling requirements taking effect in 2028.

      If you distribute products from other brands

      Distributors placing third-party branded products on the market must verify that their suppliers comply with the PPWR. The regulation also introduces secondary liability for businesses that place products on the market when the manufacturer or importer has failed to meet the relevant requirements. Reviewing supplier agreements and introducing specific PPWR compliance clauses can help manage this risk.

      Any transport packaging you use yourself, including crates, pallets and stretch film, is also subject to packaging minimisation requirements and reusable packaging targets.

      If you sell through online marketplaces

      Your first priority should be to review your EPR registrations and determine which platforms and countries will require additional declarations from 12 August 2026. Amazon and Zalando have already indicated plans to expand their EPR requirements in 2026. Sellers without valid registrations risk having their accounts suspended.

      You should also check whether the platforms you use have published specific PPWR packaging compliance requirements, including the maximum 40% empty space rule and recyclability declarations.

      Summary

      The PPWR introduces far-reaching changes to packaging requirements across several areas. Extended producer responsibility remains a central element of the regulation, but it is by no means the only obligation.

      For e-commerce businesses, the key requirements taking effect on 12 August 2026 include the maximum 40% empty space rule for shipping packaging, harmonised EPR obligations incorporating a new definition of producer that covers cross-border sales, and new responsibilities for online marketplaces to verify seller compliance. Additional packaging labelling requirements will follow in 2028. By 2030, businesses will also need to meet the applicable recyclability standards, minimum recycled content requirements and reusable packaging targets.

      None of these changes can be implemented overnight. Redesigning packaging requires time for development, testing and supply chain adjustments, while introducing reusable packaging systems can take several months.

      At EFF, we help businesses identify their PPWR obligations based on their role in the supply chain and prepare for compliance. Our support covers everything from packaging audits and EPR registrations to preparing the necessary compliance documentation. [Link]

      Frequently asked questions (FAQ)

      What is the PPWR and when does it apply?

      The Packaging and Packaging Waste Regulation (PPWR), Regulation (EU) 2024/1781, is the EU regulation governing packaging and packaging waste. Published in June 2024 and applied 12 August 2026, with packaging labelling requirements taking effect on 12 August 2028, it replaces Directive 94/62/EC and, as an EU regulation, is directly applicable in all Member States.

      I already comply with EPR requirements. Do I need to do anything else to comply with the PPWR?

      Yes. EPR is only one aspect of the PPWR. The regulation also introduces the maximum 40% empty space rule for shipping packaging, mandatory recyclability assessments, new labelling requirements from 2028 and reusable packaging targets from 2030. Existing EPR registrations may also need to be updated after 12 August 2026 to cover additional packaging types and reporting categories.

      What is the maximum 40% empty space rule, and how can I check whether my packaging complies?

      Under this rule, the space between the product and the outer walls of the shipping package, including void-fill materials, must not exceed 40% of the package’s total volume. To check compliance, measure the total volume of the package and the space occupied by the product and its necessary protective materials. If the remaining space accounts for more than 40% of the total volume, the packaging needs to be adjusted.

      I import products from Asia. What obligations does the PPWR impose on me?

      An importer assumes responsibilities equivalent to those of a producer if the overseas manufacturer has not appointed an authorised representative in the EU. These responsibilities include EPR obligations, recyclability assessments and ensuring that imported products carry compliant packaging labels. Before August 2026, you should verify that your suppliers meet the PPWR requirements concerning packaging composition, including restrictions on PFAS and SVHCs, and obtain the relevant declarations of conformity.

      I sell on Amazon and Allegro. What changes from 12 August 2026?

      Article 45 of the PPWR requires online marketplaces to collect sellers’ EPR registration numbers and verify their registration status. Amazon and Zalando already require EPR registration numbers in selected countries. From 12 August 2026, these requirements will extend to all EU countries and all sellers. Failure to maintain valid EPR registrations may result in account suspension.

      When do the new packaging labelling requirements, including QR codes, take effect?

      The requirements take effect on 12 August 2028, two years after the PPWR’s main application date. Packaging will need to carry material identification codes, waste sorting instructions, QR codes containing packaging information and, where applicable, information about reusability and recycled content.

      What will change regarding reusable packaging?

      Reusable packaging is designed for repeated use over a specified minimum number of cycles. From 1 January 2030, at least 10% of packaging used for e-commerce shipments must be reusable. Implementing a reusable packaging system, including pilot schemes, reverse logistics and selecting an appropriate packaging pooling solution, requires at least one to two years of preparation.

      What are the penalties for failing to comply with the PPWR?

      The PPWR leaves Member States responsible for determining the level of penalties, while requiring them to introduce sanctions that are “effective, proportionate and dissuasive”. Experience with existing national EPR schemes shows that fines can reach tens or even hundreds of thousands of euros. In Germany, for example, failure to register with LUCID can result in a fine of up to €200,000. Non-compliance with the PPWR may also lead to marketplace sales restrictions or products being withdrawn from the market.

      Sources

      • Regulation (EU) 2024/1781 of the European Parliament and of the Council of 22 May 2024 on packaging and packaging waste. Official Journal of the European Union, L 2024/1781, 22 June 2024.
      • European Commission. (2024). Packaging and Packaging Waste Regulation – Key Provisions for Economic Operators. ec.europa.eu/environment/packaging
      • PRO Europe. (2025). PPWR Implementation Guide for Producers and Distributors. pro-e.org
      • European Environment Agency. (2024). Packaging Waste in Europe – Key Findings from EEA Analysis. eea.europa.eu
      30 October, 2026
    • Italy: Annual VAT return requirements for 2026

      Businesses registered for VAT purposes in Italy are required to submit an annual VAT return for the 2025 reporting year. The annual return (dichiarazione annuale IVA) summarises VAT transactions carried out during the 2025 tax period and complements the information reported through periodic VAT filings.

      Purpose of the annual VAT return

      The annual VAT return provides an overview of VAT transactions reported during the year. While periodic VAT returns focus on aggregated figures, the annual return requires a breakdown of transactions based on their nature and applicable VAT rates.

      Additional transactions included in the return

      It may also include certain transactions that are not reported through periodic VAT communications, such as specific exempt supplies.

      Does filing trigger a VAT payment

      In most cases, the submission of the annual VAT return does not trigger an immediate VAT payment.

      Filing deadline

      The Italian annual VAT return for the 2025 tax year must be submitted electronically between 1 February and 30 April 2026.

      Who must file the return

      The obligation to file applies to VAT registered businesses regardless of whether they are in a net VAT payable or VAT refund position.

      Need support with Italian VAT reporting?

      Ensure correct filing and avoid compliance risks in Italy

      Book a consultation

      Electronic submission

      The annual VAT return must be submitted exclusively via electronic channels to the Italian tax authority (Agenzia delle Entrate).

      Non-established businesses

      This requirement also applies to non established companies registered for VAT purposes in Italy.


      Italian VAT refunds

      In Italy, VAT refunds are generally requested through the annual VAT return. The annual filing serves as the basis for determining whether a taxpayer is entitled to a refund of excess input VAT for the reporting period.

      Bank guarantee and “visto di conformità”

      As a rule, the refund of recoverable VAT may require the provision of a bank guarantee. However, under certain conditions, this requirement can be replaced by a certificate known as “visto di conformità”.

      What is “visto di conformità”

      This certificate verifies the alignment between the VAT return, VAT ledgers and issued invoices. The “visto di conformità” must be issued by a certified Italian chartered accountant.

      Additional documentation requirements

      Before approving the VAT refund, the Italian tax authorities may also request supporting documentation, such as copies of invoices.


      Source:

      Imprese – Che cos’è – Agenzia delle Entrate, Imprese – Modello e istruzioni – Agenzia delle Entrate

      27 May, 2026
    • Hands assembling puzzle piece over sustainability charts

      UK SRS and FCA Guidance Explained: What Changes for Sustainability Reporting?

      This month, the UK government released its long‑awaited Sustainability Reporting Standards (SRS), aligned with the International Sustainability Standards Board’s (ISSB) IFRS S1 and IFRS S2. It’s a defining moment that finally gives UK companies a clear blueprint for sustainability reporting. The draft UK Sustainability Reporting Standards (UK SRS) set out the core disclosure content based on IFRS S1 and S2, while the FCA’s CP26/5 consultation explains how those standards would be applied specifically to UK‑listed companies. In practice, the UK SRS define what must be disclosed, whereas CP26/5 sets who must report, when the rules take effect, and how they will operate within the UK Listing Rules —…

      The Scope of the UK SRS and CP26/5 Requirements

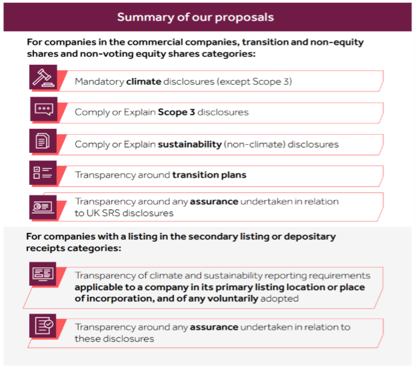
      The FCA proposes that the new rules apply to the following categories of listed companies:

      • Commercial companies (UKLR 6)
      • Non equity shares and non voting equity shares (UKLR 16)
      • Transition category (UKLR 22)
      • Secondary listing (UKLR 14)
      • Depositary receipts (UKLR 15)

      Categories excluded from the requirements

      Source: FCA Consultation Paper CP26/5 

      The FCA suggests excluding:

      • Closed-ended investment funds (UKLR 11) and open-ended investment funds (UKLR 12)
      • Shell companies (UKLR 13)
      • Debt and debt-like securities (UKLR 17)
      • Securitised derivatives (UKLR 18), as well as warrants, options, and other miscellaneous securities (UKLR 19)

      How the UK SRS Compare to IFRS and TCFD

      If you’re familiar with IFRS or the former TCFD framework, Novata has prepared a helpful comparison table summarising key differences and similarities across UK SRS, IFRS S1/S2, and TCFD.

      UK SRS IFRS S1 & S2 TCFD Framework 
      Status UK-endorsed sustainability standards (exposure drafts published) Global baseline standards issued by the ISSB Voluntary global disclosure framework for climate risks (TCFD disbanded in 2023
      Primary Objective Provide consistent, decision-useful sustainability information for UK capital markets Provide a global baseline of sustainability disclosures focussed on enterprise value Improve transparency on voluntary climate-related risks and opportunities 
      Scope SRS S1: All sustainability-related risks and opportunities 
      SRS S2: Climate-related disclosures 
      IFRS S1: General sustainability disclosures 
      IFRS S2: Climate-related disclosure 
      Climate-related risks and opportunities only 
      Materiality Focus Enterprise value (financial materiality) Enterprise value (financial materiality) Financial impacts of climate risks and opportunities 
      Structure Mirrors IFRS & TCFD structure across four core pillars Incorporates TCFD four pillars: Governance, Strategy, Risk Management, Metrics & Targets Four pillars: Governance, Strategy, Risk Management, Metrics & Targets 
      Alignment with TCFD Full incorporates and builds on TCFD principles IFRS S2 incorporates and extends TCFD Original framework 
      Prescriptiveness High: detailed, standardised disclosure requirements High: detailed, standardised disclosure requirements Moderate: principles-based guidance 
      Climate Scenario Analysis Required under SRS S2 where climate risk is material  Required under IFRS S2 Recommended 
      Transition Plans Required disclosure where applicable Required disclosure where applicable Recommended 
      Scope 1 & 2 Emissions Mandatory under SRS S2 Mandatory under IFRS S2 Recommended 
      Scope 3 Emissions Required where material, with transitional reliefs Required where material, with transitional reliefs Recommended 
      Link to Financial Statements Requirement to connect sustainability and financial reporting Explicit requirement to connect sustainability and financial reporting No formal linkage requirement 
      UK-Specific Elements May include UK-specific phasing, guidance, or regulatory interaction Explicit requirement to connect sustainability and financial reporting Not jurisdiction-specific 

      Need support with UK SRS or FCA requirements?

      Ensure your sustainability reporting is compliant and aligned with global standards

      Book a consultation

      The UK SRS Timeline and What Happens Next

      The UK government published the draft UK SRS following its 2025 consultation. The FCA is currently requesting feedback on its Consultation Paper (CP26/5), which opened on January 30th and will close on March 20th. The goal is to ensure that UK SRS align with international frameworks and improve transparency for investors, consumers, and companies.

      Expected implementation timeline

      A final FCA policy statement is expected this autumn, once the UK SRS are finalised (anticipated this spring). This would enable the new rules to take effect on 1 January 2027 — the proposed start date for mandatory UK SRS reporting for listed companies.

      FCA implementation roadmap

      In their Consultation Paper (CP26/5), the FCA lays out its proposed timeline for the implementation of the SRS


      Source: FCA Consultation Paper CP26/5 


      Conclusion

      As the UK moves toward adopting the UK Sustainability Reporting Standards, organisations should recognise that these rules signal a major shift toward more transparent, globally aligned sustainability reporting.

      How to prepare for UK SRS reporting

      By combining the content of UK SRS S1 and S2 with the FCA’s CP26/5 implementation framework, companies now have a clear understanding of what they must disclose, who will be in scope, and how reporting expectations will be phased in ahead of 2027.

      Preparing early—by strengthening data, governance, and reporting processes—will help businesses ensure compliance, meet investor expectations, and gain a strategic advantage as the UK transitions to a more consistent, investor focused sustainability disclosure regime.


      Sources 

      22 May, 2026
    • ESG Without the Mandate: A Practical Guide for Companies Under 1,000 Employees

      In October 2025, the European Parliament rejected the proposed simplifications to the CSRD and CSDDD directives, which means their final form is still taking shape. The next vote is scheduled for November. If the proposed compromise is adopted, the new thresholds for mandatory ESG reporting would come into effect no earlier than 2026, and CSDDD-related obligations would begin applying from 2029. For companies with fewer than 1,000 employees, this is a period of uncertainty—but also an opportunity to make strategic decisions.

      Does ESG reporting still apply to you?

      According to current proposals:

      • CSRD would apply to companies with more than 1,000 employees and over EUR 450 million in net turnover.
      • CSDDD would apply to companies with more than 5,000 employees and turnover above EUR 1.5 billion.

      For companies below these thresholds, this would mean one thing: the formal obligation to report may no longer apply. But this does not mean ESG stops being relevant—quite the opposite.

      ESG reporting not only helps you meet market expectations but, above all, allows you to identify risks that may translate into real financial losses—from supply chain disruptions and increasing energy costs to the potential loss of contracts.

      Why voluntary ESG reporting is worth the effort

      1. Maintaining your position in the supply chain

      According to the report Decarbonisation Is Already Here, prepared by the Climate & Strategy Foundation, 72% of SMEs using their calculator state that clients ask them about their carbon footprint—19% receive such questions regularly.

      If your company supplies goods or services to larger entities, it is worth being prepared for these inquiries. A lack of data may lead to losing a contract to a competitor who has those figures ready.

      2. Risk assessment by financial institutions

      Banks and investment funds still need to report ESG under their own regulations, and nothing indicates this will change soon. They rely heavily on data provided by their clients to meet these obligations. This means the absence of ESG policies may negatively affect the risk assessment of companies applying for financing.

      Example: A construction company with no adaptation plan for extreme weather events may be considered high-risk and receive worse loan terms—or be denied financing altogether.

      Book a non-binding consultation and learn how to meet regulatory expectations safely and efficiently.

      Contact our expert for support.

      Get in touch

      3. Insurance and climate-related risks

      Climate change affects not only energy costs and resource availability but also insurance pricing. Insurers increasingly require ESG data to assess operational risk. For example, a logistics company without a climate risk analysis may be unable to secure coverage for a warehouse in a flood-prone region. In 2022, Poland’s largest energy companies spent PLN 31 billion on emissions allowances alone—nine times more than four years earlier.

      4. Early identification of financial risks

      A properly conducted analysis of carbon footprint, resource consumption, and ecosystem impact helps identify risks before they become costly. For instance, identifying the risk of rising electricity prices and investing in your own renewable energy source can protect your operating costs in years to come.

      5. ESG as a competitive advantage

      Companies that report ESG manage costs more effectively, attract investors, and build business resilience. In municipal tenders, requirements such as fleet electrification increasingly influence contractor selection.

      Research results presented in the Ayming International ESG Barometer 2025 clearly show that businesses are developing a deeper understanding of ESG. When asked about progress in implementing selected ESG solutions, 35% of companies indicated they have already implemented e-mobility (e.g., EV infrastructure), and another 48% plan to do so. This means that staying competitive requires keeping pace with the sustainability initiatives your competitors are already implementing.

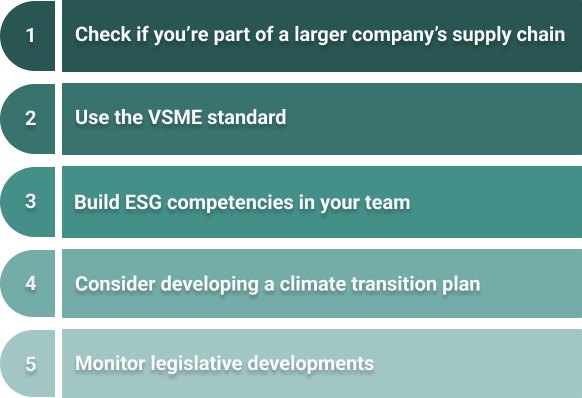
      What can you do right now?

      If your company falls below the new thresholds, you can decide how to proceed—but taking a thoughtful, strategic approach will help you make the most of this flexibility:

      1. Check whether you’re part of a larger company’s supply chain

      If your clients fall under CSRD, expect inquiries about their emissions, environmental policies, and broader ESG risks. Even without formal reporting, it is beneficial to implement basic due diligence procedures.

      2. Use the VSME standard

      The European Commission plans to launch a free portal providing guidance and reporting templates for small and medium-sized businesses. It offers a straightforward, accessible starting point that aligns with current market expectations.

      3. Build ESG competencies in your team

      Even a basic report relies on accurate data, clear processes, and team engagement. Starting early makes it easier to build toward more advanced practices over time. Begin with straightforward assessments—such as energy consumption, Scope 1 and 2 GHG emissions, or diversity policies.

      4. Consider developing a climate transition plan

      While it is not mandatory, preparing one can be highly beneficial. Companies that develop such plans are better equipped to navigate rising energy prices, evolving regulations, and increasing client expectations. In 2023, 54% of companies published a transition plan, and 40% set a net-zero target..

      5. Monitor legislative developments

      The Omnibus proposal has not been adopted, and another vote is scheduled for November. Keeping track of these developments will help you stay prepared.

      Summary: Don’t wait—act!

      Changes in CSRD and CSDDD are not merely deregulation—they signal that the EU is seeking balance between climate ambitions and business realities. For companies under 1,000 employees, this is the moment to make a conscious decision.

      ESG is here to stay. As its form, scope, and pace evolve, companies that embrace it now will not only secure regulatory clarity but also position themselves for meaningful, lasting market advantage.

      If you want to discuss how to approach ESG in your company—we’re here to help. We support companies under 1,000 employees in implementing ESG practices, building resilience, and preparing for the future.

      5 December, 2025
    • Key updates on 2026 VAT rate changes in Lithuania

      The Lithuanian parliament (Seimas) has approved a series of significant changes to the country’s VAT system, set to take effect from January 1, 2026. The reform introduces higher VAT rates for several sectors, including accommodation, culture, and heating, while also lowering the tax on books.

      Key updates

      The following changes will take place:

      • The reduced VAT rate of 9% will increase to 12%, affecting accommodation, certain transport services, and cultural events. This may result in higher prices that will affect end customers
      • The VAT on heating, hot water, and firewood will rise to the standard rate of 21%. Households and service providers will face additional costs, particularly during colder periods.
      • A reduced VAT rate from 9% to 5% will apply to books and printed or electronic publications, as well as non-periodical publications, both printed and electronic (e.g. manuals, academic texts), as a means of promoting reading and learning.

      This excludes:

      • calendars,
      • notebooks,
      • publications in which advertising constitutes more than 4/5 of content,
      • other similar printed matter.

      These measures are expected to have wide-reaching effects across the hospitality, publishing and utilities.


      Source:

      –XV-287 Lietuvos Respublikos pridėtinės vertės mokesčio įstatymo Nr. IX-751 19 straipsnio pakeitimo …

      25 November, 2025
    • 7% VAT rate for restaurants in Germany from 2026

      Starting from 1 January 2026, Germany will reinstate a 7% VAT rate on restaurants and catering services, excluding the sale of beverages. The measure was included in 2025 Tax Amendment Act as a permanent solution aiming to provide lasting support to the hospitality industries, which are facing continued economic pressure. This will also help to align Germany with neighboring countries, many of which already introduced reduced VAT rates on food services, helping restaurants near borders to remain competitive. The measure also works to simplify the complex VAT distinctions between dine-in and takeaway services.

      Update on VAT for restaurants

      The change follows the previously temporarily implemented VAT reduction during the COVID-19 pandemic, which was applied as governmental help to support restaurants and catering services in the struggling hospitality industry. In January 2024, the standard VAT rate was reintroduced and, in face of ongoing economic pressures, is now being revisited.

      Businesses can find more information in an administrative letter containing clarification on combination offers (e.g. menu including drinks) and restaurant vouchers, which are advised to be switched to multi-purpose ones, enabling customers to benefit from reduced VAT in 2026.

      Source:

      Tax Amendment Act 2025: Gesetzentwurf der Bundesregierung – Entwurf eines Steueränderungsgesetzes 2025

      12 November, 2025
    • VAT increase on unhealthy foods from 2026 in Slovakia

      The Slovak government has announced an increase in the VAT on food products with high sugar or salt content. It will raise the VAT rate from 19% to 23%, starting from 1 January 2026. The decision has been made as a part of a broader Tax Amendment Act 2025 and its goal is both to strengthen additional revenue as a fiscal consolidation measure, as well as to discourage overconsumption of sugar and salt as a public health initiative.

      New VAT rate

      The new VAT rate will supposedly affect about one-quarter of current food products, all of which have higher contents of sugar and salt, namely:

      • soft drinks,
      • confectionery,
      • chips,
      • processed snacks.

      Some foodstuffs and products will be exempt from the increase, such as:

      • salt and sugar as basic raw ingredients,
      • baby food, food for diabetics, dairy drinks, yogurts,
      • 100% fruit juices
      • other staple or essential food items.

      Businesses, especially ones that produce borderline products (e.g. “low-sugar” variants, snacks with moderate amounts of salt), will need to review their product classification and determine whether their goods will be subject to the higher 23% VAT rate. This means a necessary update to IT systems, pricing models and invoicing processes to adequately reflect the new rate. Producers, suppliers and retailers are advised to reassess cost structures and margins while awaiting further clarification from Ministry of Finance and Health.

      Source:

      – Tax Amendment Act 2025: Verejnosť a médiá : Udalosti : NRSR: Poslanci schválili balík konsolidačných opatrení na budúci rok…

      12 November, 2025
    • EPR in Germany: What you need to know when selling products abroad

      Are you currently selling or planning to sell products to customers in Germany? Regardless of your sales model whether B2B, B2C, via your own online shop, or through platforms like Amazon or eBay, you are likely subject to Germany’s Extended Producer Responsibility (EPR) regulations.

      What should you know about EPR as a seller, distributor, or manufacturer?

      EPR places environmental responsibility on companies for the entire lifecycle of their products. Whether you’re a manufacturer or simply a seller, you must comply with specific obligations. Failure to do so can result in fines, blocked listings, or even a complete ban on selling in Germany. Below you’ll find all the essential information to help you stay compliant.

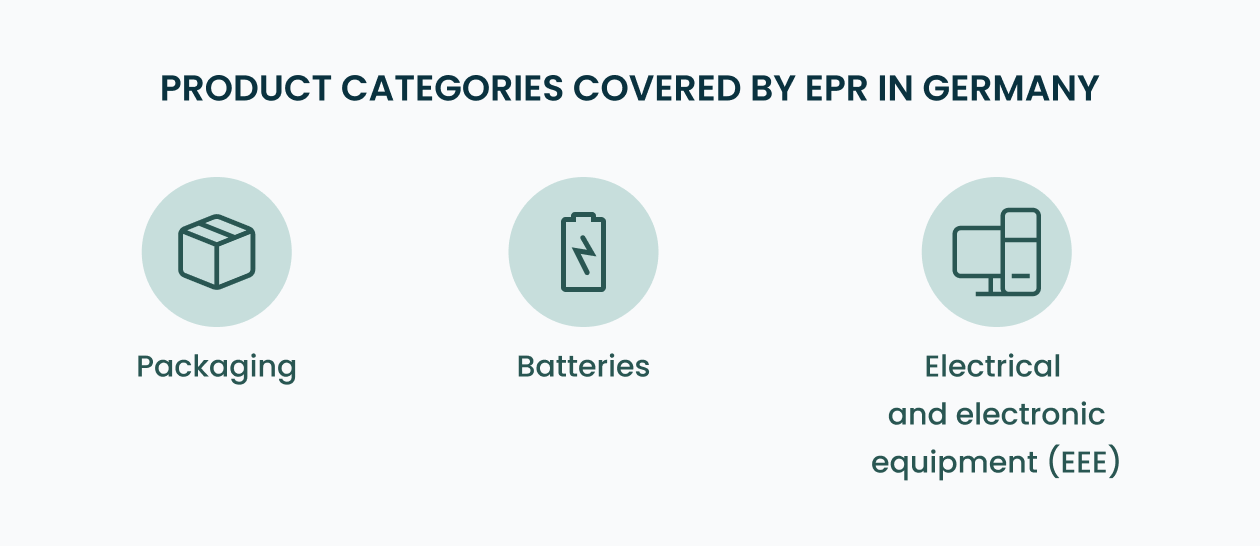
      Extended Producer Responsibility (Erweiterte Herstellerverantwortung – EHV) is a legal framework that requires companies to manage their products after their end-of-life. It applies to several product categories: packaging, batteries, electrical and electronic equipment (EEE)

      Under the “polluter pays” principle, if you profit from selling regulated products, you are also responsible for their environmental impact. This includes recycling, disposal, and financial contributions to waste management systems.

      Who must comply?

      1. Manufacturers and brand owners
        • Produce goods and sell under their own brand
        • Outsource production but sell under their own brand (private label)
      2. Exporters and cross-border sellers
        • Sell directly to German consumers via e-commerce
        • Operate online shops or sales platforms with delivery to Germany
      3. Retailers and mail-order companies operating in Germany
        • Sell online or via mail order within Germany
        • Deliver products directly to end customers
      4. Importers and distributors
        • Import goods into Germany
        • Resell them (wholesale or retail)

      If your business sells physical goods in Germany and those products generate waste such as packaging, electronic devices or batteries, you are likely subject to EPR regulations. These rules apply regardless of where your company is bases.

      How to comply with EPR in Germany: Step-by-step guide

      Before starting salesOngoing obligations
      1. Identify which products are subject to EPR1. Report the volume of the products and packaging
      2. Register with the relevant authorities:2. Pay environmental fees
      3. Sign a contract with a dual system operator3. Keep your registration data up to date
      4. Obtain your EPR registration number
      5. Appoint an authorized representative in Germany (if you don’t have a local entity)

      New plastic tax – what you should know

      From 1 January 2024, Germany introduced an environmental levy on single-use plastic products. This includes takeaway food containers, plastic cups, bags, and wet wipes.

      Obligations for producers and importers:

      • Register in the DIVID system
      • Track quantities sold from 2024
      • Submit annual reports
      • Pay the calculated levy

      Funds collected are used to reimburse municipalities for waste management and environmental protection, reinforcing Germany’s commitment to sustainability.

      Want to ensure safe and hassle-free compliance?

      Book a consultation with our experts.

      Contact us

      What are the risks of non-compliance?

      Ignoring EPR obligations can lead to serious consequences:

      • Fines – substantial financial penalties
      • Blocked listings – marketplaces may suspend your products
      • Sales bans – in extreme cases, complete exclusion from the German market

      Beyond legal risks, non-compliance can damage trust with customers and business partners.

      Not sure if EPR applies to your business?We’re here to help.

      Navigating EPR requirements can be complex—especially for companies entering the German market. At EFF, we specialize in supporting businesses at every stage. From registration with LUCID and Stiftung EAR to appointing a local representative and ongoing reporting—we provide full support to help you stay compliant.

      Act now – Avoid costs. Gain advantage. Be responsible.

      Environmental regulations like EPR are here to stay and are becoming stricter. Governments and consumers expect greater accountability. Acting now helps you avoid financial and operational risks and positions your brand as a sustainability leader.


      Source:

      – Zentrale Stelle Verpackungsregister (ZSVR). (n.d.). Verpackungsregister [Website].https://www.verpackungsregister.org/
      – Stiftung elektro‑altgeräte register (stiftung ear). (n.d.). stiftung ear – Your authority for implementing ElektroG & BattG [Website]. https://www.stiftung-ear.de/en/

      22 October, 2025
    • Limiting ESG reporting – A path to climate catastrophe?

      In recent years, climate policy has become one of the pillars of sustainable development strategies for companies worldwide. The obligation to report on ESG (Environmental, Social, Governance) was designed to increase transparency in environmental actions and to encourage businesses to take tangible preventive, corrective, and adaptive measures in response to climate change. However, plans to ease ESG reporting requirements, included in the European Commission’s so-called Omnibus proposal, may have serious consequences – both for the environment and the economy.

      Slowing down climate action – Short-term gain, long-term loss

      Although the proposal to reduce the number of companies required to report on ESG has its advantages and may be attractive to businesses seeking to avoid additional administrative costs, these short-term savings will not offset long-term consequences. Without transparent reporting, companies will find it easier to limit investments in green technologies and climate adaptation. This means:

      • Fewer companies will monitor their greenhouse gas emissions and energy efficiency.
      • Decarbonisation initiatives in production and supply chains will be scaled back.
      • Businesses will be less inclined to implement adaptation strategies, such as protection against extreme weather events.

      It is therefore crucial to emphasise the objective of the Omnibus. Simplifying reporting requirements is not intended to weaken climate strategies. On the contrary – by freeing up company resources from complex reporting processes, the goal is to give them space to implement actions as quickly as possible. In short: more action, less bureaucracy – a step towards real results.

      Companies must remember that without adequate mitigation measures, climate change will accelerate, and its effects will cut across multiple areas.

      Learn more about the Omnibus!

      Read our article on this topic.

      Read more

      Here are a few examples of real consequences:

      • Extreme weather events will damage infrastructure – Severe storms, floods, and heatwaves will become more frequent and intense. Without proper preparation and adaptation, companies exposed to these threats will face enormous financial losses. An example is the 2021 floods in Germany, which cost the economy over EUR 30 billion.
      • Disruptions in raw material supplies and supply chains – Droughts and other weather anomalies will adversely affect agriculture, among other sectors, leading to higher food and raw material prices. Companies unprepared for such circumstances will face serious operational challenges.
      • Higher insurance premiums and financial losses – Insurers are already raising premiums for companies in areas threatened by climate change. As the problem escalates, companies will be forced to pay more, impacting their profitability.
      • Loss of investor and consumer trust – Investors increasingly factor ESG into financial decisions. Companies that scale back reporting and climate action risk losing access to financing and facing capital outflows.

      Why is ESG transparency crucial?

      Responsible ESG reporting is not merely a bureaucratic requirement – it is a mechanism that drives companies to take real climate action. Transparency enables progress evaluation and increases pressure on businesses to implement sustainable strategies on a broad scale.

      If the limitation of ESG reporting obligations results in halting activities in these areas, it will be a step backwards in the fight against climate change. The growing climate risk and its consequences will cost global economies billions of dollars annually. If companies fail to act now, in a few years they will face even greater losses – both financial and environmental. Climate change does not wait for reports – it spreads regardless of political decisions. Businesses that ignore responsibility for their actions today will face unavoidable costs tomorrow.


      Sources:

      – Powódź w Niemczech. 30 mld euro na fundusz odbudowy [Floods in Germany: EUR 30 billion reconstruction fund]

      21 August, 2025

    Contact form

    Contact us and we will respond within 24 hours!
    Kontakt
    Close
    Would you like to change the market?
    Select area of operation
    You will be redirected to another page for the selected market
    Polska
    Jesteś tutaj
    United Kingdom
    Go to page